Life insurance is an asset class. It deserves the same level of ongoing oversight as other financial assets
- Aurum Insurance Partners
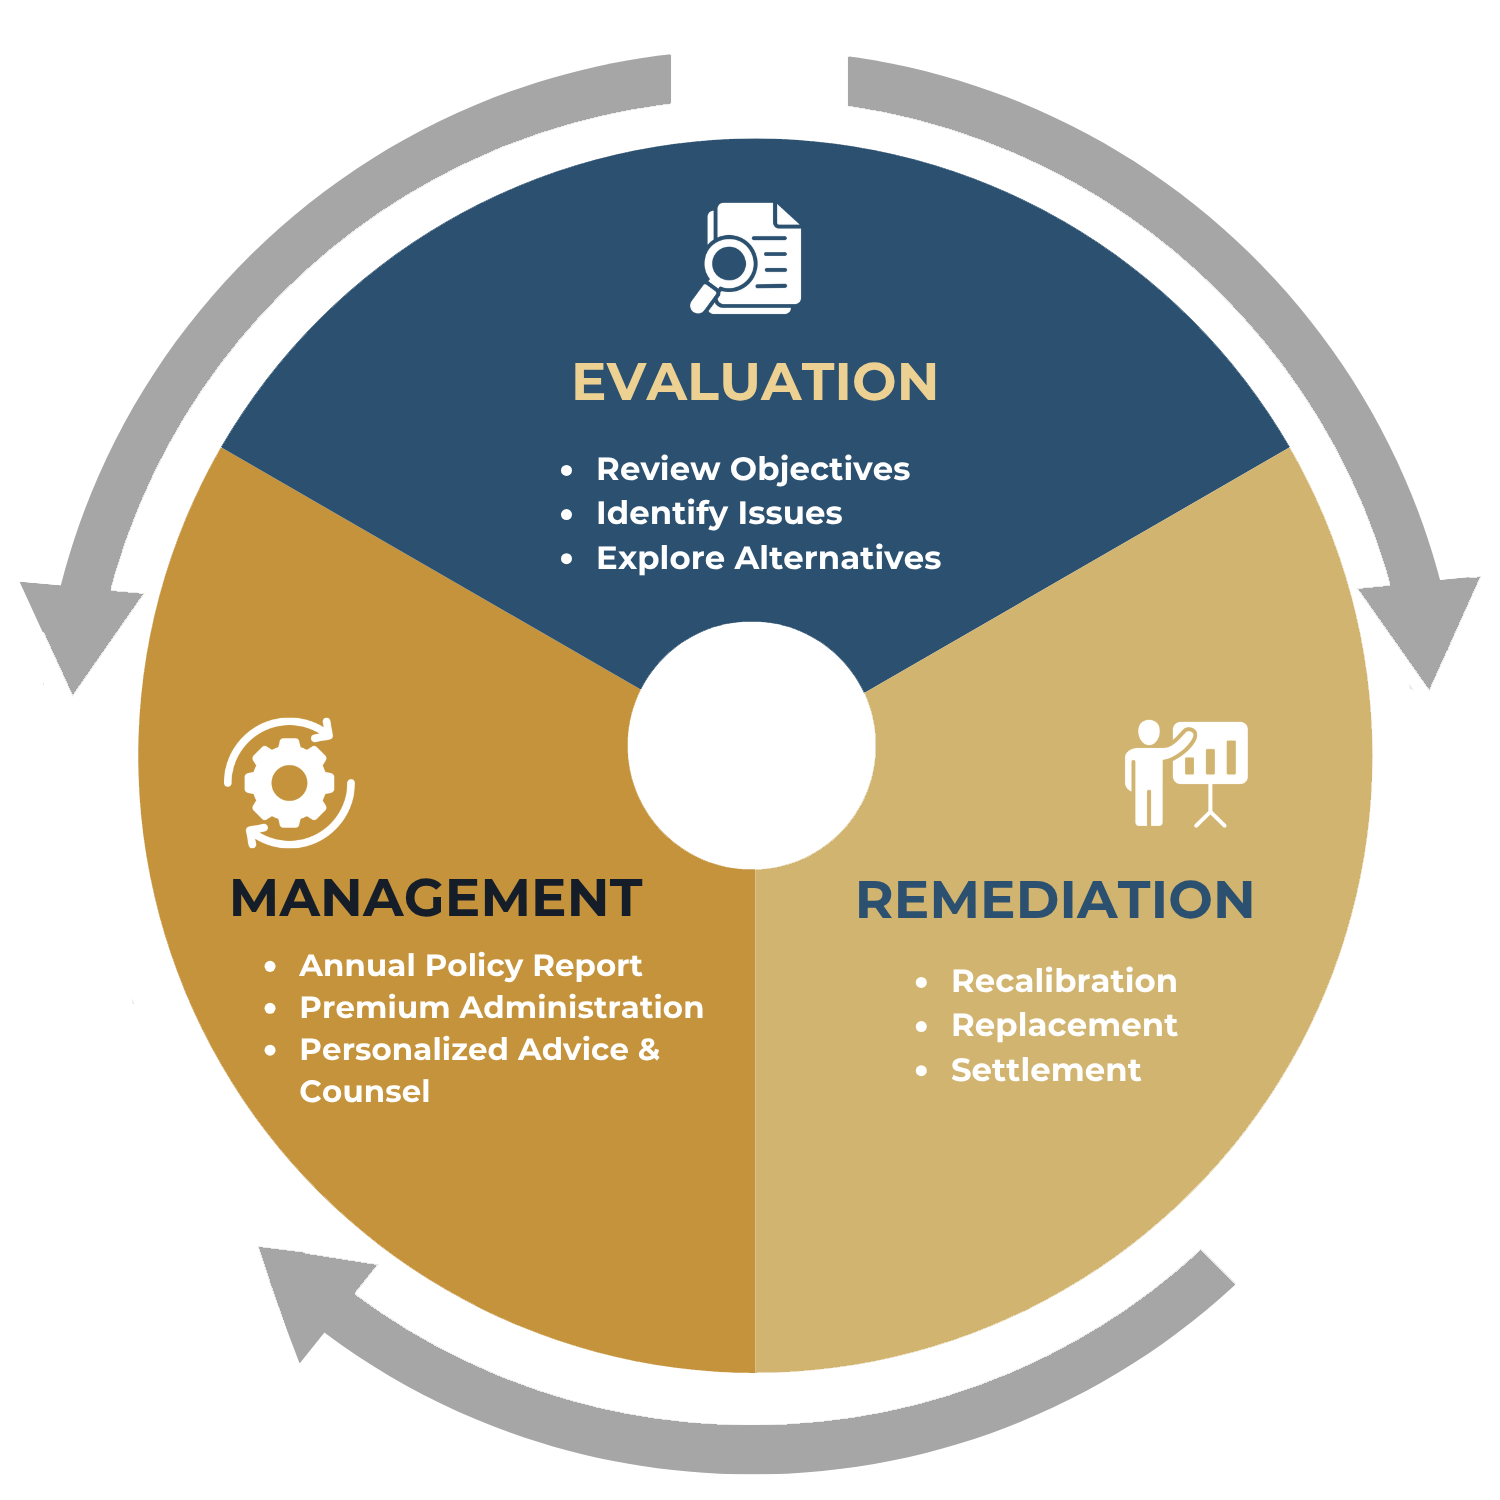
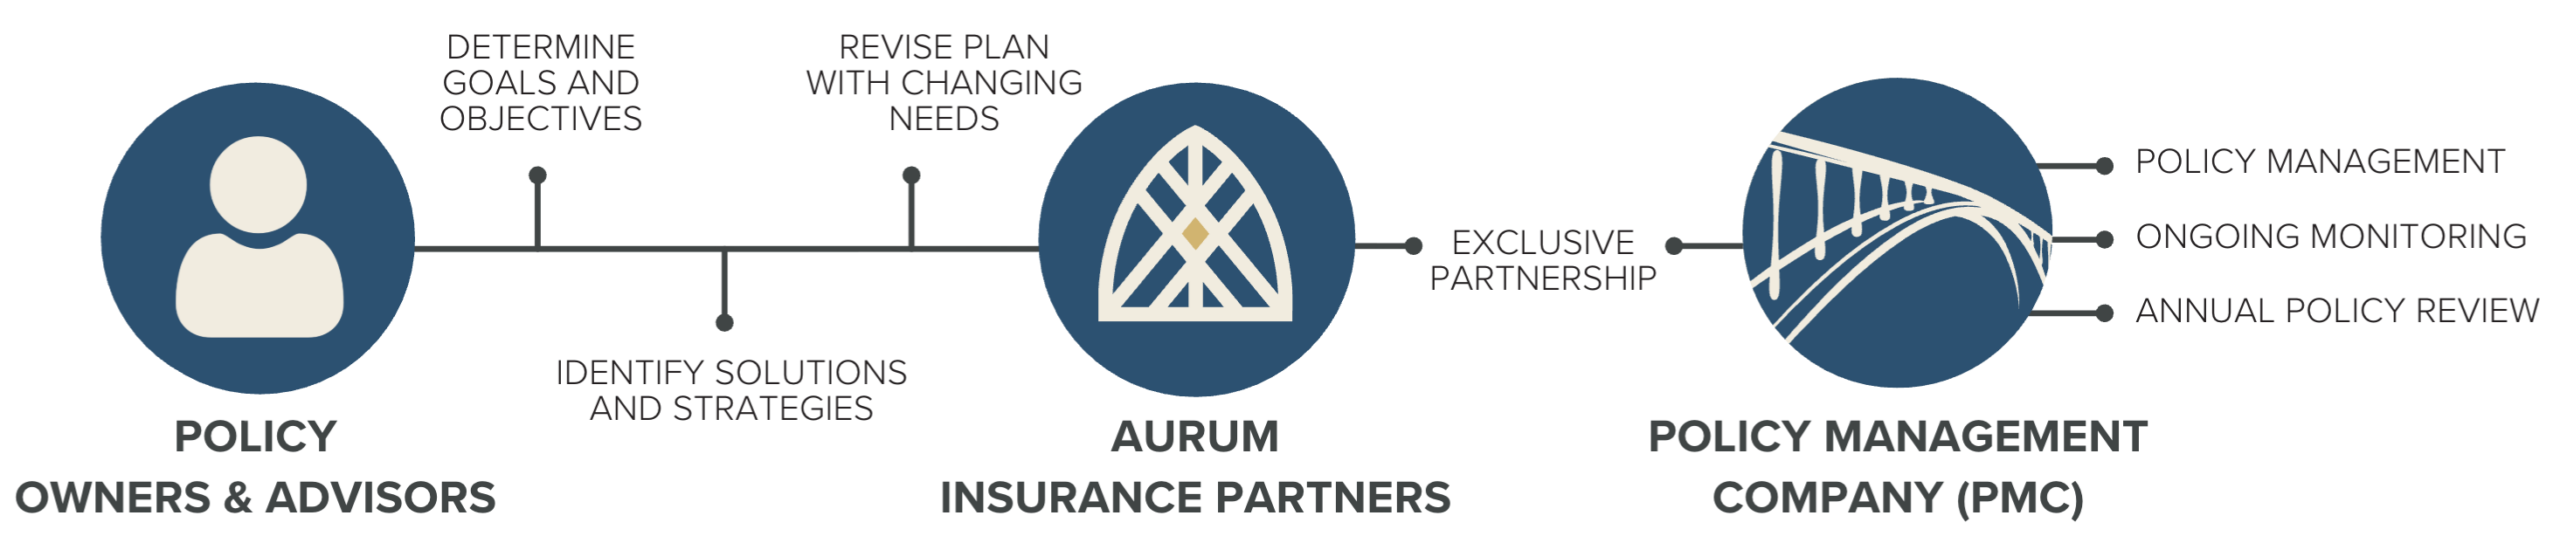
Disciplined Process for Bridging Policy Expectations with Results
1. Set Up & Design
Begin by completing a policy management questionnaire with your insurance advisor to determine your policy design objectives and guidelines for the policy. Any original documentation and current statements will be gathered and archived.
• What are the long-term objectives for the policy?
• Is the policy meeting the current needs?
• How should the performance be measured?
2. Monitoring & Management
The policy is monitored based on the priorities and guidelines as designed. Based on the service level, alerts, reminders and notifications communicate the current performance while service requests and policy changes are facilitated to completion in coordination with your insurance advisor.
• Is the policy following the design guidelines?
• Are premiums being paid on time and in the correct amount?
• What inforce changes are needed?
3. Analysis & Reporting
After each policy anniversary, a thorough review is completed based on inforce illustrations and current policy values compared to the design and objectives. Policy performance is assessed, and an annual report summarizes the current health and status of the coverage.
• How is the policy performing? Are there any risks or opportunities?
• Are the policy, riders, features, and insurance company meeting expectations?
• Has anything changed in the current situation?
4. Recommendations
Working with the PMC and using the annual policy review as a guide, your insurance advisor may provide recommendations to improve the current coverage or take corrective action as needed. Recommendations can be the result of a change in needs, underperformance of a policy, or created by other industry developments. They may include recalibrating the current policy, evaluating new coverage, or updating the policy management design.
• Does the policy align with future goals and objectives?
• What actions would improve the coverage?
• Are there alternative options for the client?
Policy Management Partnership
As life insurance policies grow more complex, ongoing policy management represents a meaningful opportunity to protect outcomes and strengthen client relationships. At Aurum Insurance Partners, we believe policies deserve the same level of attention as other significant assets: active oversight, objective evaluation, and thoughtful adjustments over time.
Aurum leads this process with experienced guidance, disciplined analysis, and access to specialized policy management resources, including Valmark’s Policy Management Company. Our role is to help advisors and clients evaluate performance, identify opportunities for improvement, and keep coverage aligned with expectations as needs evolve.
Risks Affecting Policy Performance
Policy Administration
-
Premium payments and timing
-
Withdrawal and loan payments
-
Non-enacted planned events
-
Utilization/termination of riders and conversion options
-
Beneficiary, address or trustee changes
Insurance Companies
-
Insurer strength and stability
-
Administrative and servicing errors
-
Limited communication to owners and trustees
-
Changes to products and features
Policy Performance
-
Crediting rate and dividends
-
Sub-account allocation and performance
-
Guarantee and shadow account challenges
-
Cost of insurance increases
Industry & Environment
-
Low interest rate environment
-
Changing laws and fiduciary requirements
-
New products and solutions in the marketplace
-
Tax and estate plan implications
Benefits of Active Policy Management
Through objective analysis and ongoing policy management, the Policy Management Company:
-
Ensures life insurance policies perform as designed and continue to meet clients’ needs
-
Mitigates the risk of policy lapse or underperformance
-
Resolves errors and prevents issues that can cause problems
-
Confirms premium payments and planned changes are made
-
Identifies opportunities to maximize the value of the policies

Policy Management
Service Levels
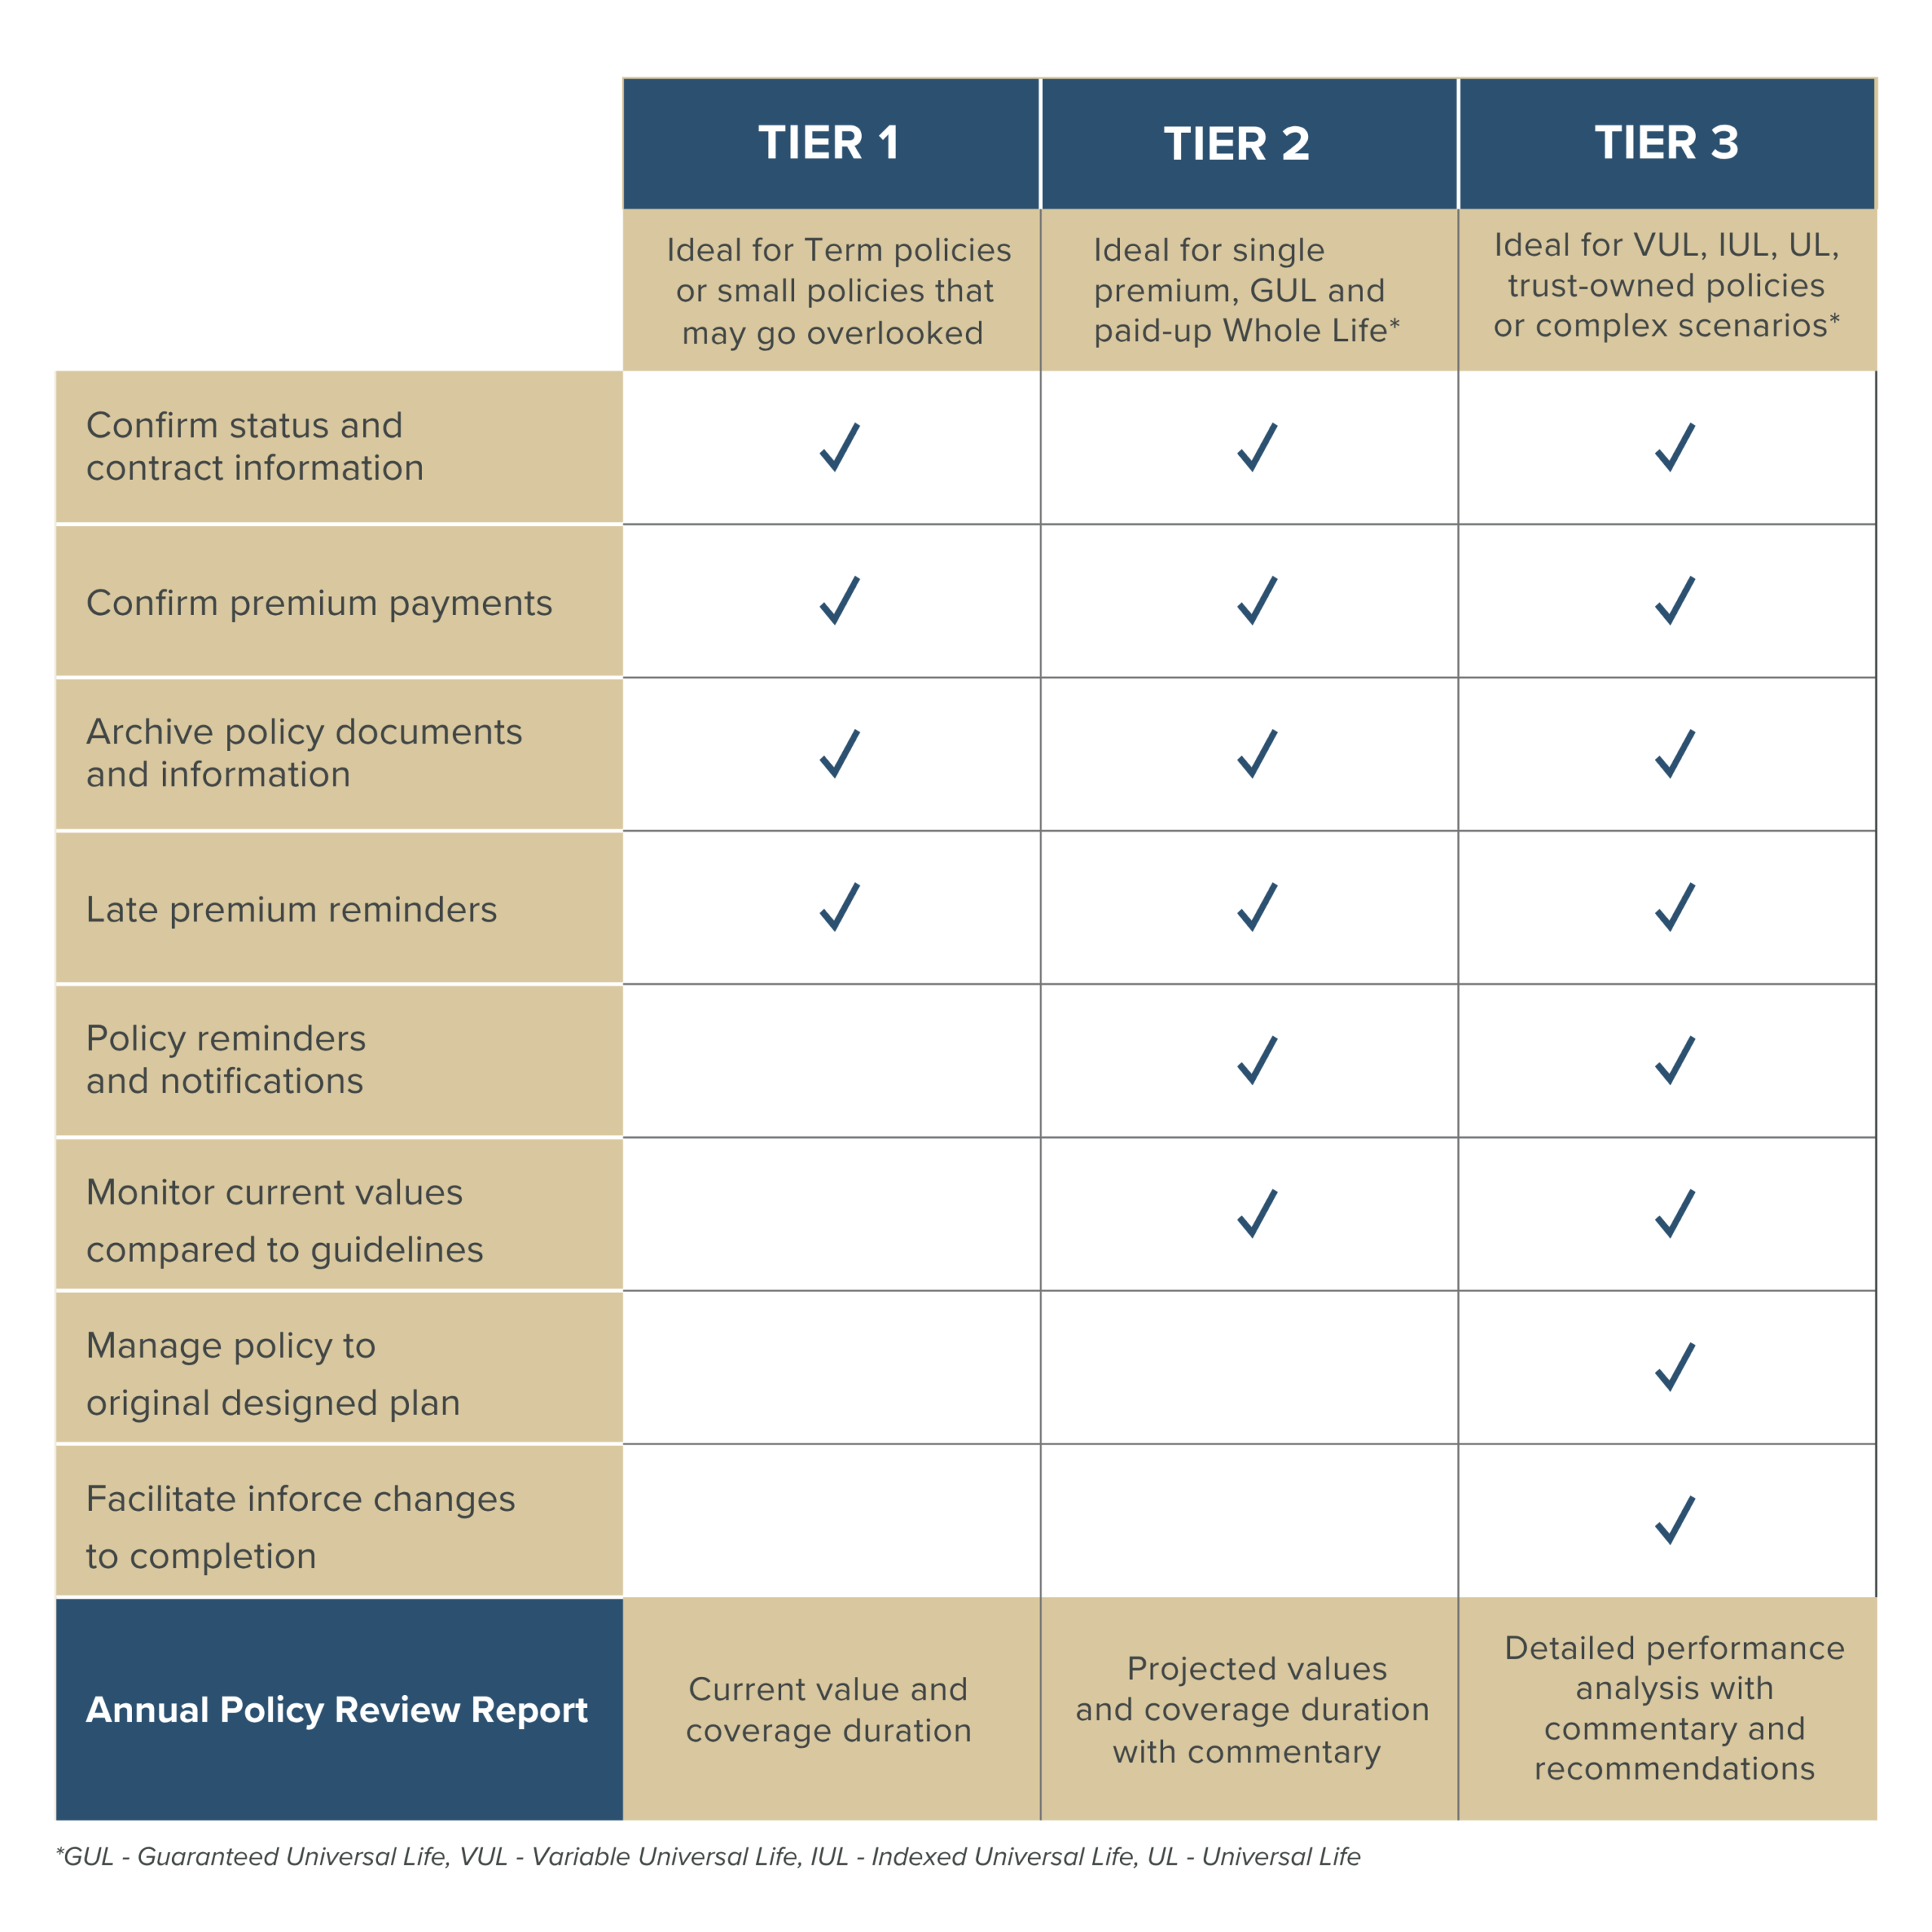
Different types of policies require different levels of management: Tailor the service to fit your policy.